

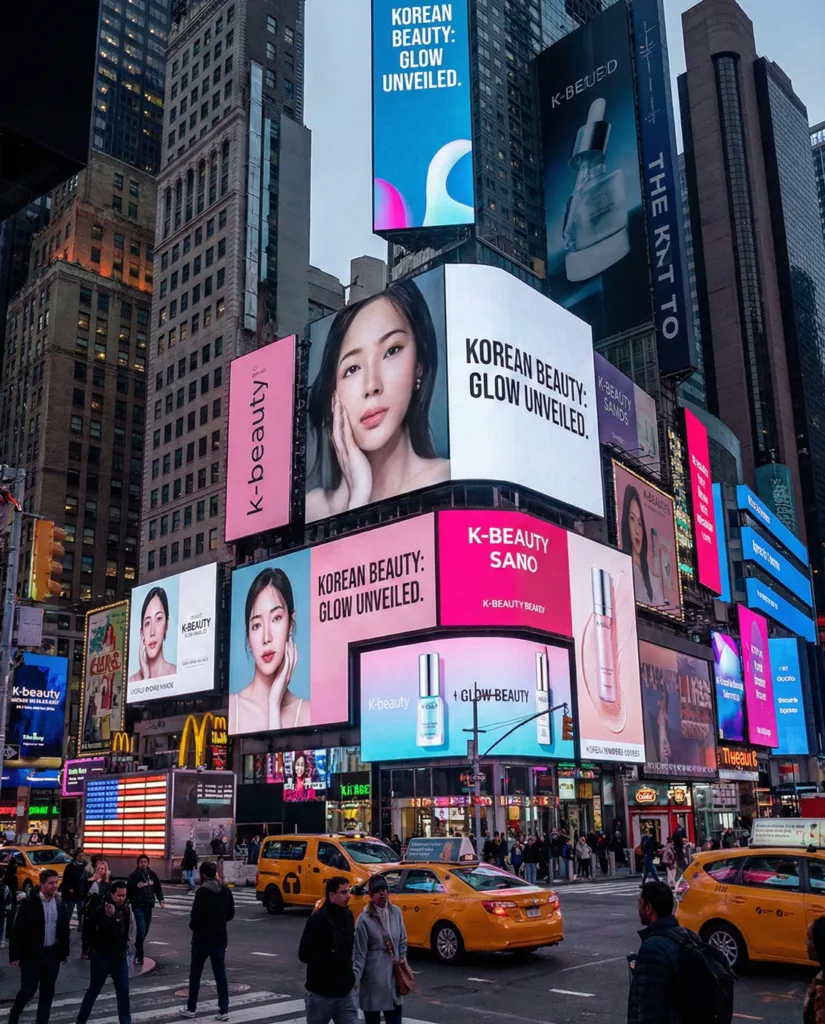
In 2025, Korea overtook France to rank No. 1in the U.S. cosmetics import market. This is not just a trend. It is structural growth proven by numbers. Add the return of Chinese tourists and the windfall from China-Japan tensions, and multiple growth engines are firing at once in the K-beauty sector.
BITPRESS verified the facts and picked the top 5 beneficiary stocks to watch in 2026.
Fact check ①: Is K-beauty really No. 1 in the U.S.?
→ True.
According to official statistics from the Ministry of Food and Drug Safety, Korea's cosmetics exports in 2024 rose 20.6% year on year to $10.2 billion (about KRW 15 trillion) , a record high. The U.S. market posted the strongest growth, and, along with Japan, Korea rose to become the No. 1 countryfor cosmetics imports in the U.S.
As of the first half of 2025, exports to the U.S. stood at $1.02 billion (18.5% of total exports) , having grown more than twofold over the past five years and still growing. On Amazon, once K-beauty's main channel, Medicube has now ranked No. 1 overall in beauty on Amazon Prime Day, and Boots, the UK's largest drugstore chain, even runs a dedicated ‘Korean Skincare’ section.
💬 Note | Drugstore: A retail channel that sells medicines together with household goods and cosmetics. Boots in the UK and CVS and Walgreens in the U.S. are typical examples, and they serve as footholds for beauty brands entering offline retail.
Fact check ②: Are the inflow of Chinese tourists and the windfall from China-Japan tensions real?
→ True, and backed by data.
According to Yanolja Research's deep-learning demand forecasting model, foreign visitors to Korea in 2026 are projected to reach 20.36 million , an all-time high. One analysis also suggests that if the ‘balloon effect’ of China-Japan tensions materializes, Chinese tourists could reach up to 7 million, bringing total visitors to 21.26 million.
💬 Note | Balloon effect: Just as squeezing one side of a balloon makes the other side bulge, when demand for a particular country is suppressed, demand shifts to a nearby substitute market. A typical example is Chinese tourists who canceled trips to Japan because of China-Japan tensions and turned to Korea instead.
There is precedent in past data. During the THAAD dispute, 10–13% of Chinese tourism demand shifted to Japan, and this time the movement is going the other way. In fact, visitors to Korea from January to October 2025 totaled 15.82 million , up 15.2%from the same period a year earlier, with notable increases in Chinese and Japanese tourists.
When Chinese tourists visit Korea, cosmetics shopping centered on Myeong-dong and duty-free shops is already an established pattern, so a recovery in inbound travel translates directly into gains for K-beauty's domestic sales channels.
Top 5 K-beauty beneficiaries for 2026
Experts forecast 2026 cosmetics export growth, in dollar terms, of 15% , higher than in 2025. The following five stocks were selected on three pillars: expansion into U.S. and European channels, ODM re-rating and the inbound tourism boost.
💬 Note | ODM(Original Design Manufacturing): A model in which the manufacturer handles everything from product design and development to production and supplies the products under the client's brand. Cosmax and Kolmar Korea are typical examples.
💬 Note | Re-rating: An upward revision of the valuation multiple applied to a stock. It happens when earnings improve or growth potential is recognized anew, and it is a key driver of share price gains.
No. 1: APR (278470) — top pick among indie brands
APR, which runs the Medicube and APR brands, is named in brokerage reports as the top pick in the sectoramong K-beauty indie brands. Building on brand power already proven on Amazon in the U.S., 2026, when its expansion into offline channels such as Ulta and Sephora gets into full swing, is seen as the period with the highest earnings visibility. In 2025, its share price posted a year-on-year gain of +114% , making it the top performer in the K-beauty sector.
No. 2: Silicon2 (257720) — the key pipeline for K-beauty distribution in Europe
Silicon2 has placed large numbers of K-beauty indie brands in European retail channels such as Boots in the UK, drawing attention as a structural beneficiary of Europe's growth momentum. At a time when cosmetics export growth to Europe has soared into the 40% range, it is the stock most closely tied to that performance. K-beauty's penetration in Europe is still only about half that of North America, leaving plenty of room to grow.
No. 3: Cosmax (192820) — the global ODM leader
In 2025, Cosmax posted the best results in its history, with revenue of KRW 2.3988 trillion and operating profit of KRW 195.8 billion. It succeeded in reducing its dependence on China by securing orders from U.S. and Japanese indie brands, and in 2026, rapid growth in sun care in Thailand and expansion of body and sun care in the U.S. are additional growth drivers. Its ODM PER currently stands at around 12.2 times, a level seen as having corrected enough from its past high (17.8 times).
No. 4: Kolmar Korea (161890) — global No. 1 in sun care, a buy-the-dip zone
Kolmar Korea, which manufactures a large share of the world's sunscreen, is the global No. 1 sun care ODM company, and as of February 2026 its share price is around KRW 82,500. The average target price of 22 analysts is KRW 119,182 , implying upside of about +28.7% from the current price. Brokerages maintain buy ratings with a target price of KRW 90,000, judging it to be a buy-the-dip zone now that earnings estimates have been cut enough.
No. 5: d'Alba Global (317530) — a candidate to close the valuation gap
d'Alba Global has grown into one of Korea's leading indie brands, and its shares are expected to gain momentum from closing the valuation gapwith APR. In 2025, its share price rose relatively little (+3%) compared with APR, but as brand companies enter a period of even higher earnings expectations in 2026, the potential for a re-rating is coming into focus.
💬 Note | Valuation gap: A state in which valuations have diverged among companies with similar business models and growth prospects. Share prices rise when the lagging stock is re-rated toward the level of the leader over time.
Risk factors: optimism alone won't do
Looking at the 2024–2025 pattern, the K-beauty sector has repeatedly followed a ‘strong first half, weak second half’ cycle of an overheated first half → a disappointing second half. The balloon effect of China-Japan tensions is still a ‘forecast,’ not a confirmed figure, and the U.S. Trump administration's tariff policy, along with language and regulatory barriers to entering Europe, are real risks. Rather than short-term trading, a medium- to long-term approach that steadily tracks export data and quarterly earnings is recommended.
BITPRESS Insight
In K-beauty's next phase, the variable that separates the real winners is not ‘how much they sell’ but ‘through which channels they sell’ . Beyond the online highway of Amazon, the moment a brand lands on offline shelves such as Ulta, Sephora and Boots, its TAM (total addressable market) expands several times over. For investors, a stronger signal than “top Amazon ranking” data is offline reorder data. The point at which offline sales in the U.S. and Europe begin to exceed 30% of total overseas sales at APR and d'Alba Global will be this sector's real re-rating trigger.
⚠️ Investment notice: This article is for informational purposes only and is not a recommendation to buy or sell any specific stock. Final investment decisions and responsibility rest with the investor.






